Does Homeowners Insurance Cover Roof Replacement?
Discovering that your home needs a new roof can be an overwhelming experience. Between worrying about the safety of your home and wondering how you are going to pay for a major construction project, it is easy to feel stressed. One of the very first questions homeowners along the Wasatch Front ask us is whether their homeowners insurance will cover the cost of a full roof replacement.
The short answer is: it depends on what caused the damage. Homeowners insurance is designed to protect you against sudden, accidental damage from covered perils. It is not, however, a maintenance policy that pays for normal wear and tear as your home ages.
At Red Peaks Roofing Inc, we understand that navigating the intersection of roofing services and insurance policies can be confusing and frustrating. Whether you are dealing with recent storm damage or just noticing missing shingles, understanding how your policy works, what is covered, and how to approach the claims process is critical to protecting your investment.
When Will Insurance Pay for a New Roof?
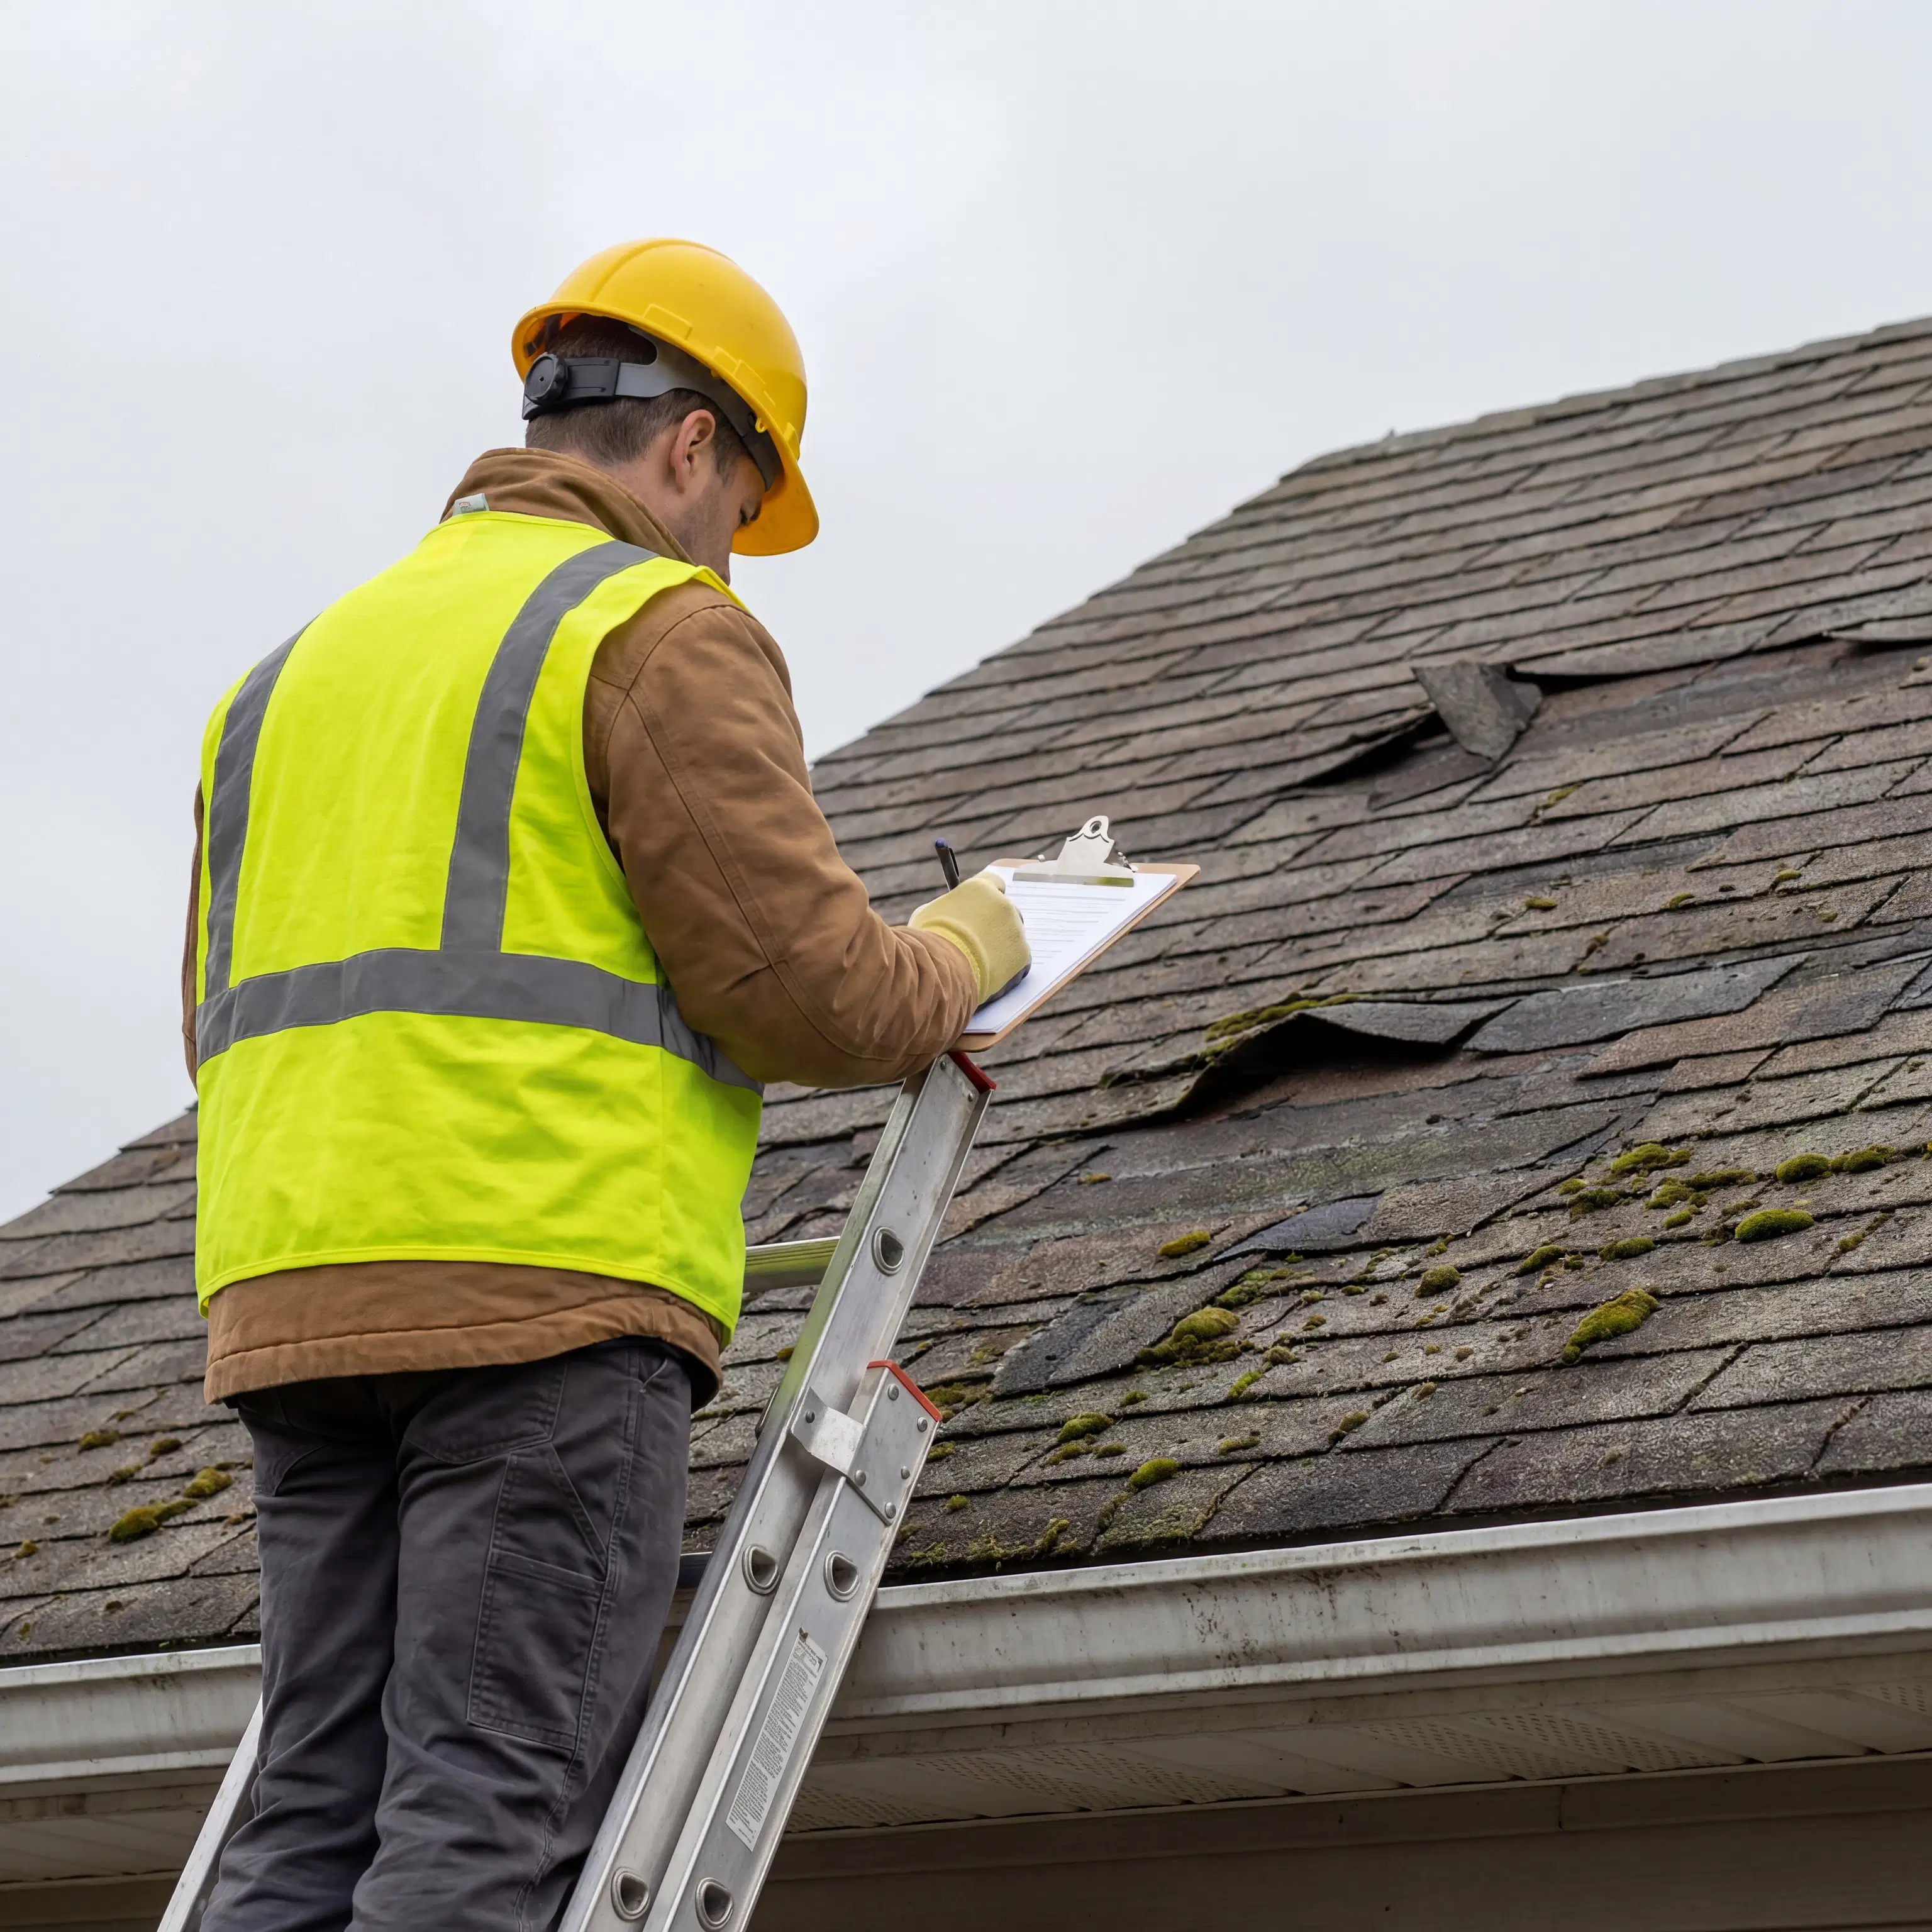
To determine if your roof replacement will be covered, you first need to identify the root cause of the problem. Standard homeowners insurance policies generally cover roof damage caused by sudden, unpreventable weather events. In Utah, this most commonly includes severe windstorms, hail, and the weight of heavy winter snow or ice dams.
If a severe thunderstorm rolls through and localized high winds rip a section of shingles off your roof, or if a hailstorm batters your property and severely damages the structural integrity of your shingles, your insurance company will likely approve a claim. In these scenarios, the damage was immediate and out of your control.
Conversely, insurance companies will rarely cover a roof replacement if the issue stems from age, neglect, or lack of maintenance. If your asphalt shingle roof is 25 years old, nearing the end of its expected lifespan, and simply begins to leak during a rainstorm, the insurance adjuster will likely attribute the failure to normal wear and tear. This is why regular inspections are so important. Knowing how to tell if your roof needs to be repaired or completely replaced before a catastrophic leak occurs can save you thousands of dollars.
Actual Cash Value vs. Replacement Cost
Even if your claim is approved, the amount your insurance company pays depends heavily on the specific terms of your policy. There are two primary types of coverage:
- Replacement Cost Value (RCV): This is the more comprehensive option. If you have an RCV policy, the insurance company will pay to replace your damaged roof with brand-new materials of comparable quality, minus your deductible. They do not deduct money for the age or depreciation of your old roof.
- Actual Cash Value (ACV): If you have an ACV policy, the insurance payout will account for the depreciation of your roof. For example, if your roof was expected to last 20 years and was 10 years old when a storm destroyed it, the insurance company will only pay out a fraction of what a new roof costs today.
Understanding homeowners insurance roof replacement coverage criteria before a storm hits is the best way to avoid nasty surprises when you file a claim. If you are ever unsure about the condition of your roof, scheduling a thorough evaluation for residential roof replacements can give you a clear baseline of your roof's health.
Navigating the Claims Process and Avoiding Scams
One of the biggest pain points for homeowners after a major weather event is dealing with the sudden influx of "storm chasers"—out-of-state roofing companies that flood neighborhoods after a storm, promising free roofs and pressuring residents into signing contracts. Unfortunately, these fly-by-night operations often perform subpar work, provide zero long-term warranties, and leave town before problems arise, creating widespread skepticism toward roofing contractors.
When hiring a professional to repair your home, local reputation matters. You want a licensed, bonded, and insured contractor who understands the local building codes and the unique demands of our high-desert climate. Look for companies that provide transparent, detailed, and accurate pricing estimates without relying on high-pressure sales tactics.
How We Help with Your Claim
Filing an insurance claim can be a tedious process involving complex paperwork, meetings with adjusters, and back-and-forth negotiations. Many homeowners feel outmatched by their insurance company.
That is where proper residential insurance claims assistance becomes invaluable. A reputable local contractor will advocate for you. Our team meticulously documents the storm damage using photos and detailed reports, meets with the insurance adjuster on-site to ensure they see the full extent of the damage, and ensures that the final payout reflects the true cost of the necessary repairs. We can even offer guidance on how to appeal a denied roof insurance claim if the initial adjuster missed crucial evidence of wind or hail impacts.
Managing Costs: Deductibles and Upfront Expenses
Even with a fully approved replacement cost claim, you are still responsible for paying your policy's deductible. Depending on your coverage, this deductible can range from a fixed amount (like $1,000) to a percentage of your home's total insured value, which can easily equate to several thousand dollars.
Furthermore, delayed insurance claim payouts can be frustrating, especially when you need immediate repairs to protect your home's interior from water damage. A quality contractor should not demand full payment up front before materials arrive, but covering your deductible and managing cash flow while waiting for the insurance check to clear can be stressful.
To help bridge this gap, many property owners take advantage of flexible payment plans. Exploring residential financing options allows you to manage your deductible or fund upgrades—such as transitioning from standard asphalt to a more durable metal roof—without draining your savings account all at once. Financing roof replacement deductible options and project upgrades helps ensure you get a durable, high-quality roof installed immediately, rather than waiting for insurance red tape to clear.
Get the Honest Answers You Need
Figuring out whether your insurance will cover your roof shouldn't be a guessing game, and you shouldn't have to navigate it alone. If you suspect your home has suffered weather-related damage, or if you simply want an honest assessment of your aging roof, Red Peaks Roofing Inc is here to help.
We pride ourselves on providing the Point of the Mountain and surrounding communities with trustworthy, transparent service. From the initial inspection to the final sweep of your yard, we focus on quality craftsmanship and reliable communication. Contact us today to schedule an inspection, and let our local experts help you protect your home.